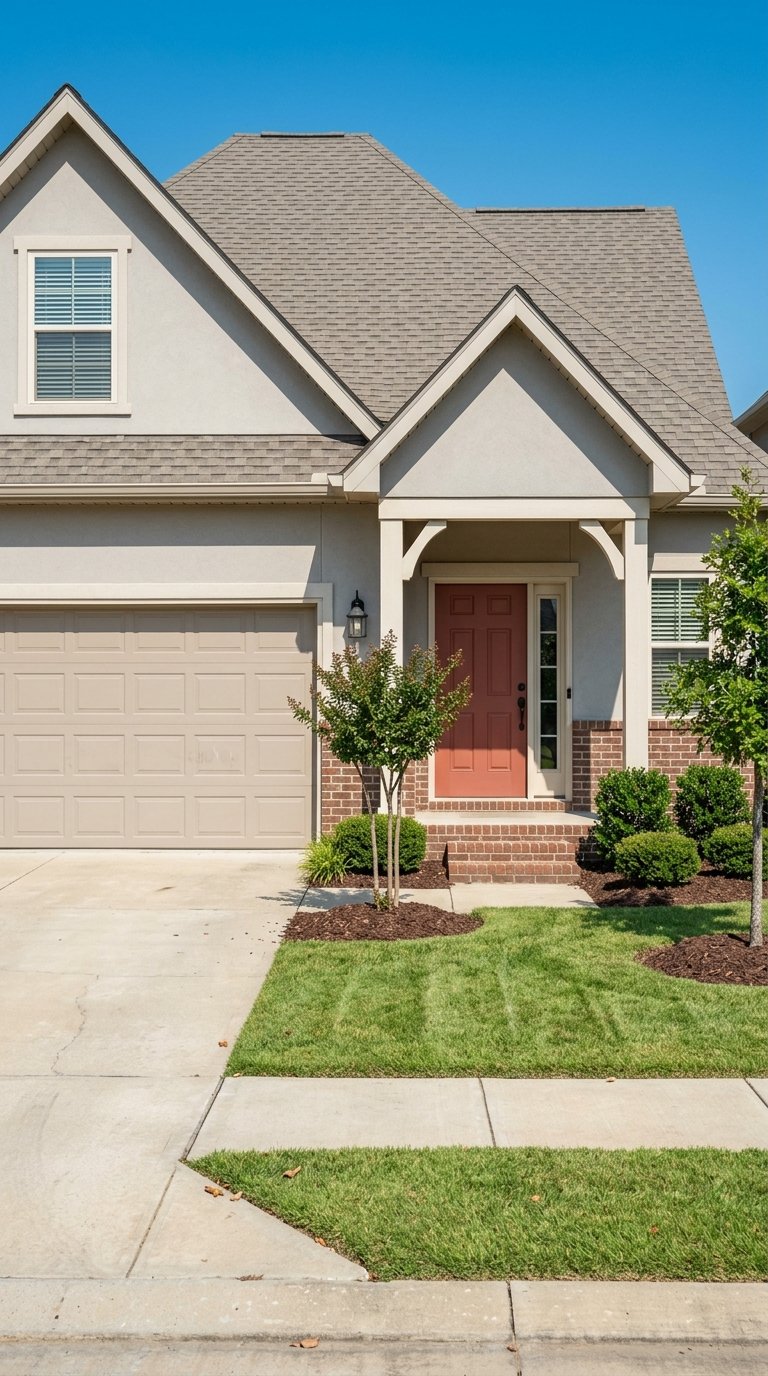
"Must contract on or after 09/01/2026 and close by 12/15/2026." That line sits near the bottom of a D.R. Horton financing flyer attached to homes in Montage, the builder's community in Mustang. Above it, in much larger type, is the number that matters to anyone shopping or selling in the mid-$200s right now: a 5.50% fixed rate on FHA and conventional loans for certain homes.
Freddie Mac's survey for the week of October 1, 2026 put the national average 30-year fixed rate at 7.28%, up from 7.03% the week before and 6.34% a year earlier. So a buyer touring a Mustang resale home this month may be comparing it with a new house that comes with a rate about 1.78 points lower. That gap shows up in the monthly payment, not the list price. A resale seller who answers it only by cutting the price is using a weaker tool than the one the builder is using.
The rate comes with a lender, a deadline, and a pool
The fine print decides who can actually get that rate. According to D.R. Horton's offer terms, which were last revised 09/02/26:
- The buyer has to finance through DHI Mortgage, the builder's affiliated lender, to get the advertised rate. Buying the home doesn't require using DHI, but the rate does.
- The contract must be signed on or after September 1, 2026, and the loan must close by December 15, 2026.
- The rate comes from a pool of funds D.R. Horton has locked in, and it lasts only until that pool runs out or the rate expires.
- Not every borrower qualifies, and some buyers may need to pay points to get the advertised rate.
- The offer applies only to certain homes, and only when the buyer will live in the home as a principal residence.
As of today, October 4, that close-by date is about ten weeks away. That gives the offer a clear window, and it also gives competing resale sellers a clear window to respond. D.R. Horton's own example uses an FHA loan on a $282,990 home. It lists a 6.212% APR and an estimated total monthly payment of $2,157, which includes taxes, mortgage insurance, homeowners insurance, and HOA dues. Montage's community page showed homes listed from $225,000 to $289,990. That price band overlaps much of Mustang's resale entry tier.
What 1.78 points is worth on a Mustang-priced loan
Here's an illustrative example, not a quote. It assumes a $270,000 loan on a 30-year fixed term and counts principal and interest only, before taxes, insurance, or mortgage insurance.
| Rate scenario | Approx. monthly principal & interest | Approx. first-year total |
|---|---|---|
| 7.28%, the Oct. 1, 2026 national average | about $1,847 | about $22,170 |
| 5.50%, the builder-arranged rate | about $1,533 | about $18,400 |
| Difference | about $314 per month | about $3,770 per year |
A buyer who's comparing the two homes on a phone calculator sees that $314 right away. To close the same monthly gap with price alone, a resale seller would need to cut far more than a few thousand dollars. Lowering the loan amount by $10,000 at 7.28% saves less than $70 a month in principal and interest. That's why a price cut is a weak answer to a rate offer: the buyer feels the rate in every monthly payment.
Why builders are spending money on rates this fall
Builders have reasons to push incentives right now. The Journal Record reported on October 2, 2026 that Oklahoma City home sales slowed sharply in August while inventory climbed. The report also said months of supply and days on market had stretched well past recent years, and that homes were selling for noticeably less than their first asking price. The median sale price held near $280,000 in August 2026. Federal Reserve data for the Oklahoma City metro showed 6,732 active listings in September 2026, with a median of 57 days on market that month. Those numbers are for the whole metro. We didn't find Mustang-only monthly resale figures, so treat them as the regional backdrop, not as Mustang's own numbers.
Mustang's builder communities fit that picture. Colony Fine Homes calls Wild Horse Canyon a newly opened section, with homes starting at $243,000. It has also posted reductions on some homes, including one from $266,900 to $258,900 and another from $261,000 to $252,900. Homes by Taber lists Canyons and Scissortail Crossing as now selling, with displayed starting prices of $268,490, and Frisco Park as a grand opening. Taber also advertises a fixed rate with closing costs covered on select homes. Its offer page shows both 4.99% and 5.49%, though, and its eligible-home list didn't confirm that any Mustang address qualifies. Buyers should get current terms directly from the builder. The Builder's Collective showed eight quick move-in homes at Mustang Park: six active, one pending, and one under construction. Above that range, Mashburn Faires listed two Mustang Ridge homes as available now at $367,500 and $377,500.
Taken together, Mustang buyers shopping between $225,000 and about $290,000 have several new-build choices. Some come with financing offers and some with posted price cuts. Many of the houses are finished and ready for a fast close.
A seller's answer is a credit the buyer can turn into a lower rate
A resale seller can offer the same kind of help the builder does. Instead of taking money off the price, the seller offers a credit at closing, and the buyer's lender applies it to a rate buydown. The Consumer Financial Protection Bureau explains the two kinds. Discount points are paid up front for a lower interest rate that lasts for the life of the loan. A temporary buydown, such as a 2-1, is a seller or third-party subsidy that lowers the payment only for a set period. The note rate stays the same underneath.
How much a seller can contribute depends on the buyer's loan type:
- VA loans. VA.gov treats seller credits for normal loan closing costs, including discount points and temporary buydown funds, separately from "seller concessions." Concessions are capped at 4% of the home's reasonable value and include things like paying the VA funding fee or paying off the buyer's debts.
- USDA loans. USDA's handbook caps seller and other interested-party contributions at 6% of the sales price and lists discount points that lower the rate as an eligible use. Seller-paid repairs and buyer-agent fees don't count toward the cap.
- FHA and conventional loans. These programs have their own limits on contributions from interested parties, and the conventional limits vary with the down payment. The buyer's lender should confirm the exact cap for the specific loan before an offer is written around it.
A credit has to be built into the contract on purpose. The buyer's lender needs to know early that a seller credit is coming and how it'll be applied, because the lender sets the price of points and has to account for a temporary buydown correctly. This post isn't financial advice. Every buyer's rate depends on their credit profile and the lender's pricing that day.
Where the next round of new homes is coming from
The City of Mustang's report dated October 2, 2026 counts 87 available lots out of 388 across eight subdivisions inside city limits. Spitler Lake Estates 3 has the most, with 22 available. Wild Horse Canyon 3 has 9 of 108 left, Hunter's Hill 5 has 10, and Magnolia Trace 6 is down to one. Most of what's coming next is a different kind of housing than the detached homes being discounted now. Riverwood Addition is a 61-lot duplex subdivision on SW 89th Street between Mustang Road and Sara Road, with storm sewer going in now. Calvary Court will have 16 townhouse units at 948 W. State Highway 152. Clear Springs Senior Independent Living, near W. SH-152 and Clear Springs Road, is close to 70% complete on 43 units. Spitler Lake Estates Section 4 has nearly finished grading.
Road work is happening on the west side too. The 16-inch waterline along SH-152, from just west of Mustang Road to Clear Springs, is finished. Resurfacing on Clear Springs Road between SW 89th and SH-152 is scheduled to start October 14, 2026, during fall break. New signal equipment along SH-152, paid for with a $560,000 grant, is expected to start going in this fall, and the city expects it to cut congestion delays on the corridor by 20% to 30%. Construction at SW 89th and Mustang Road is expected to begin in summer 2027.
For anyone selling a detached resale home in town, this fall's competition comes mostly from finished builder homes with deadline-driven financing, not from a wave of new lots.
Quick questions
Does the 5.50% rate apply to every Montage home? No. D.R. Horton says it applies to certain homes in select Oklahoma communities, requires financing through DHI Mortgage, and lasts only while the pool of funds holds out.
Is a temporary buydown the same as a lower rate? No. The CFPB describes it as a subsidy that lowers payments for part of the loan term, while the note rate stays where it is.
Are those metro figures Mustang's numbers? No. The 6,732 active listings and 57-day median for September 2026 cover the whole Oklahoma City metro. We couldn't find Mustang-only monthly resale figures.
If you're getting ready to list a Mustang home in the mid-$200s before the builders' December deadlines, it helps to know how your price and a possible buydown credit compare with the monthly payments buyers are seeing on new homes. Christy Kruckeberg can run those numbers with you and your buyer's lender in mind. Start with Get Your Free Home Valuation, and we'll build the credit math from there.